FTR's Eric Starks: truck utilization may be near 100% and contract rates could climb toward 20% in 2027 — but fuel cash flow decides which carriers keep the gains
Speaking Oct. 28 in Dallas, the FTR chairman credited data-center construction and improving manufacturing for demand, pointed to non-domiciled CDL and training-provider constraints for the capacity squeeze, and warned that smaller carriers paying for diesel today while waiting to collect are the recovery's exposed edge.
Summarized from The Trucker.
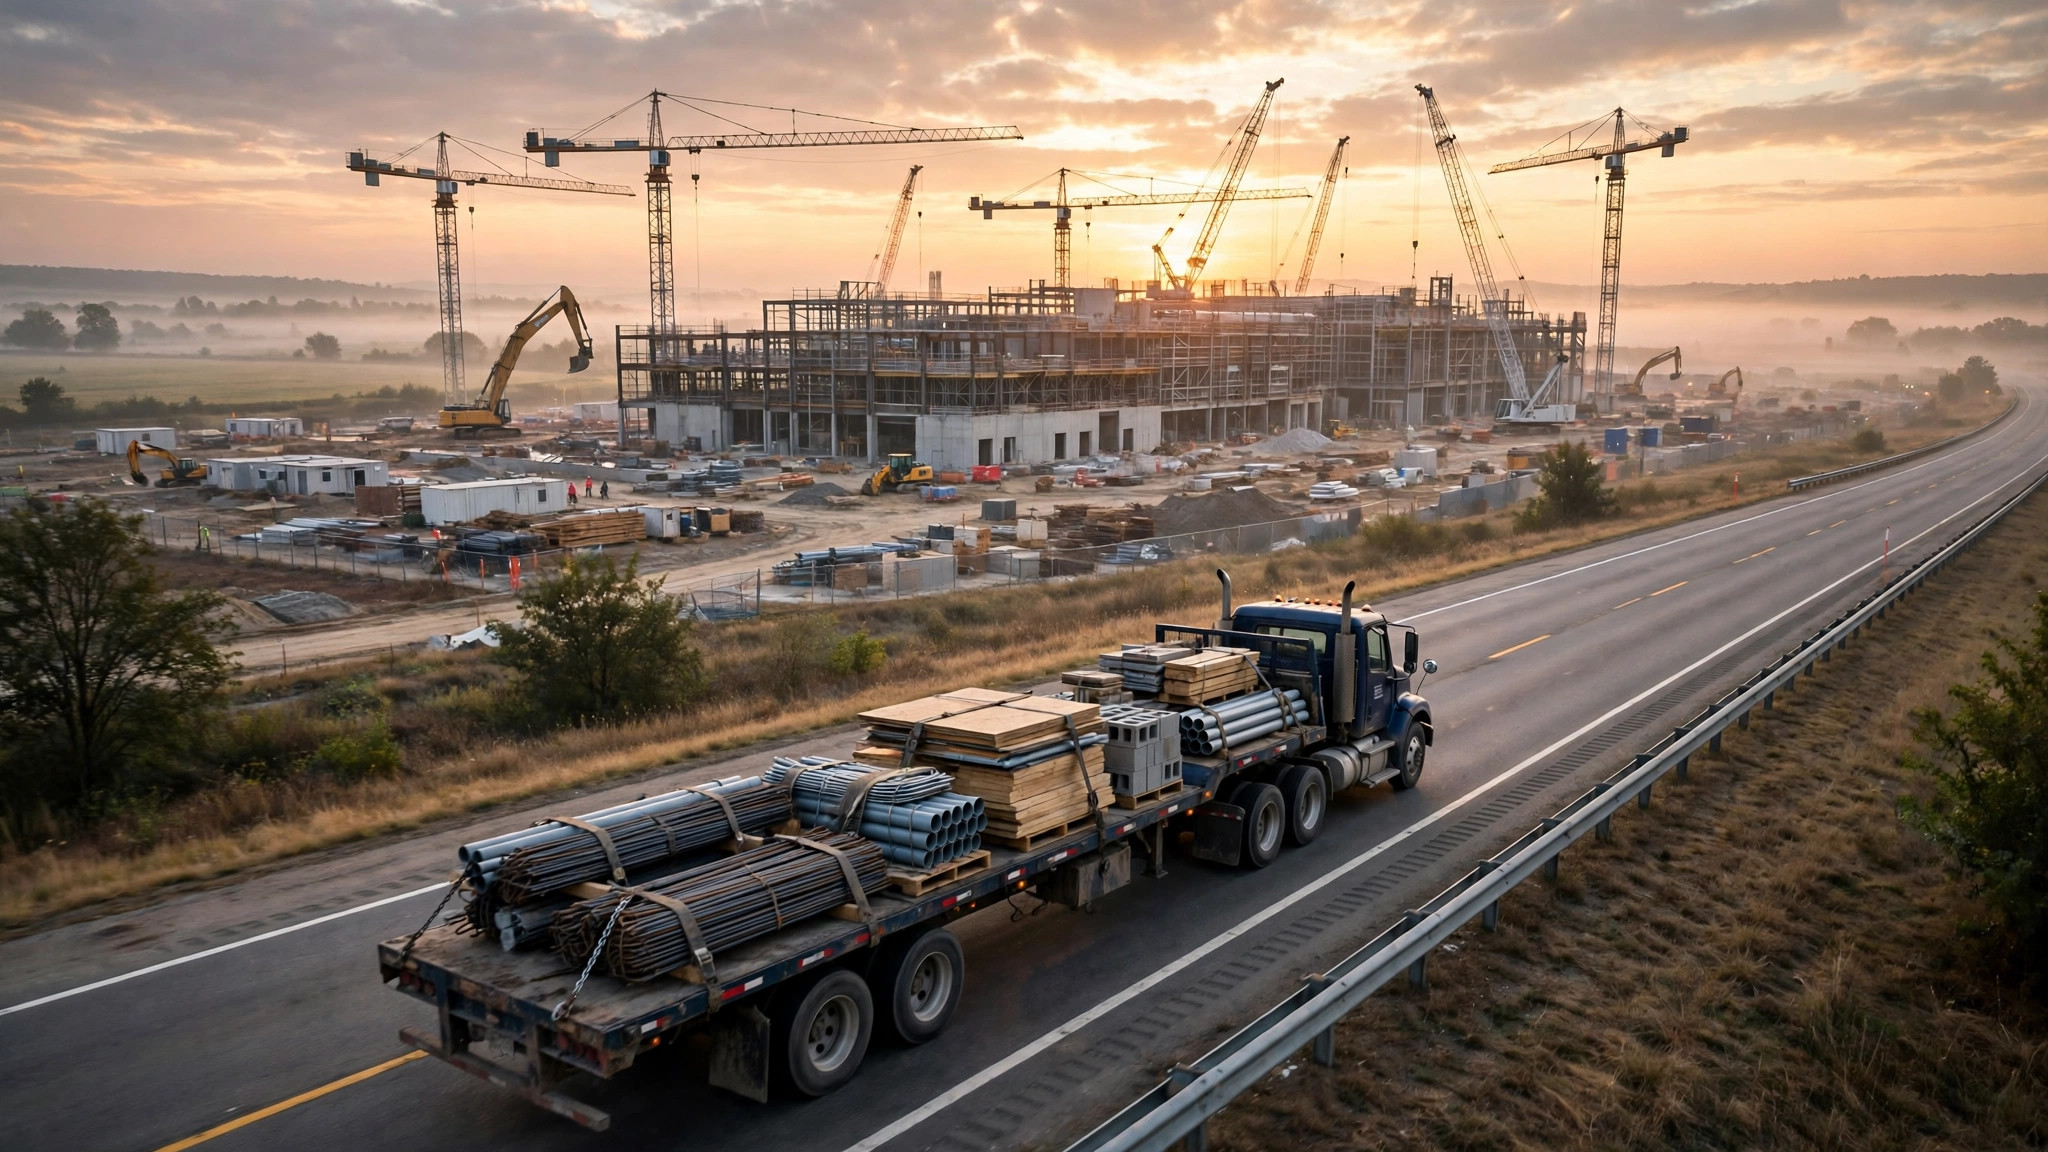
Image: Illustration: AI-generated by CDLWire
The freight recovery is arriving, and FTR’s chairman says the carriers who keep its gains will be decided less by the rate on the load than by the week they spend waiting to be paid for it. Eric Starks of FTR Transportation Intelligence laid out that outlook on Wednesday, Oct. 28, at the Women In Trucking Association’s Accelerate! Conference & Expo in Dallas, according to The Trucker on Nov. 3: data center construction and improving manufacturing activity are supporting freight demand, tight hauling capacity is putting upward pressure on rates, and fuel bills and other expenses are eating the gains unevenly — hardest at smaller fleets and owner-operators who pay for diesel today and collect from customers later.
The demand side of his case starts with a segment most drivers would not name first. One of the biggest influences on freight demand is data center construction, Starks said. The facilities require materials and equipment, creating demand beyond the trucks that deliver directly to job sites. FTR dug into the connection after flatbed tightened more quickly than other segments, and industry participants repeatedly pointed to data centers, as a direct source of freight or as competing demand for equipment. Equipment committed to one project is unavailable for another customer’s freight, even one with no connection to data centers. Starks expects the activity to support demand at least into mid-2027, with a potential correction beyond that if construction gets ahead of demand. Manufacturing also improved, in industrial production outside high-tech and an upward trend in inflation-adjusted capital goods orders, while housing provided little momentum.
His capacity measure is the number to remember. FTR’s active truck utilization compares the trucks needed to move freight with the trucks that have drivers and are available to haul cargo; a parked, driverless truck is not usable capacity. The 10-year average is 92%. Starks said preliminary analysis suggested utilization could be near 100%, an unusually tight level, and revised data could show it reaching that mark. He attributed the squeeze to freight demand combined with constraints on the driver pool, including changes affecting non-domiciled commercial driver’s licenses and training providers. His outlook calls for utilization to stay elevated before easing during 2027, with a risk tight conditions persist longer. Asked about repossessed equipment, he added a distinction that matters for anyone reading tractor counts as capacity: a broader measure still shows vehicles sitting outside active service, and equipment available for purchase is not equipment ready to move a load.
The rate charts he showed carry their own warning label. Charts using Truckstop.com data showed weekly broker-posted spot rates through week 41 of 2026, with year-over-year comparisons of 46.7% for dry van, 44.1% for refrigerated and 43% for flatbed. Those are all-in rates including fuel, Starks emphasized, so the increases should not be read as equivalent gains in carrier revenue after fuel expenses. Contract rates have also strengthened as shippers seek agreements that ensure their freight will move; FTR’s contract-rate forecast, which excludes fuel surcharges, shows year-over-year increases approaching 20% during 2027 before slowing later in the year, with the rate index itself continuing to climb before leveling off — meaning slower growth would leave shippers paying rates above earlier levels, not back at them. “Am I trying to lock in capacity, or am I trying to lock in rates?” Starks asked. “And right now, capacity is the winner. You’re trying to lock down capacity to make sure that you can get your stuff moved when you want it moved.”
On the cost side, Starks warned that diesel will remain a pressure point through winter. His presentation cited an Energy Information Administration national on-highway diesel average of $6.276 per gallon for Oct. 19, and pointed to low distillate inventories, exports and seasonal heating demand as factors supporting prices — distillate fuels include diesel and heating oil, so winter heating demand pressures the same supply. Tariffs and uncertainty around equipment-related regulations add further complications for fleets making purchasing and replacement decisions, he said.
The cash-flow distinction is where the outlook turns from market weather into business survival. A carrier can earn money on a load and still fail to finance the work until payment arrives. Larger fleets generally have more access to capital and more sophisticated fuel surcharge arrangements, Starks said, while smaller operations have less room to absorb the timing gap between buying diesel and collecting freight revenue, and the longer fuel prices stay high, the more pressure that creates. He raised one possibility as a hypothesis rather than an established trend: some owner-operators and small-fleet operators could leave their businesses and move into larger fleets, shifting capacity into bigger operations without removing every affected driver or truck from the industry.
For a driver or small fleet planning 2027, the usable version of Starks’ outlook is this: price is moving your way — utilization near historic tightness and contract increases approaching 20% are not a soft market’s numbers — but the recovery pays out through a fuel bill that arrives daily and a receivable that arrives in weeks. Negotiate the surcharge mechanism and the payment terms with the same energy as the rate itself, keep the cash reserve the winter diesel market demands, and treat parked, driverless equipment in any capacity statistic as what Starks says it is: metal, not capacity.
Sources
Related coverage
 October 31, 2026 · Fuel & ratesCovenant's CEO expects double-digit truckload rate hikes again in 2027 — and says ELD enforcement will keep pulling capacity out
 October 30, 2026 · Fuel & ratesSpot rates slipped $0.023 this week — reefer broke a four-year seasonal pattern — but every segment is still up more than 40% on the year
 October 29, 2026 · Fuel & ratesShipper spending surged 32.1% in the third quarter — the biggest jump since 2021 — while freight volumes barely moved
Comments
Loading comments…