Spot rates rose more than 4% while diesel fell 3.5% — the early-November jump FreightWaves calls unusual
FreightWaves' National Truckload Index climbed more than 4% from late October to its highest dry van levels since July, even as diesel truck stop prices fell roughly 3.5% over the same period — a divergence analysts tie to tight capacity and an October Logistics Manager Index inventory reading of 66.9, the highest since 2022, as delayed holiday freight spilled onto the spot market.
Summarized from FreightWaves.
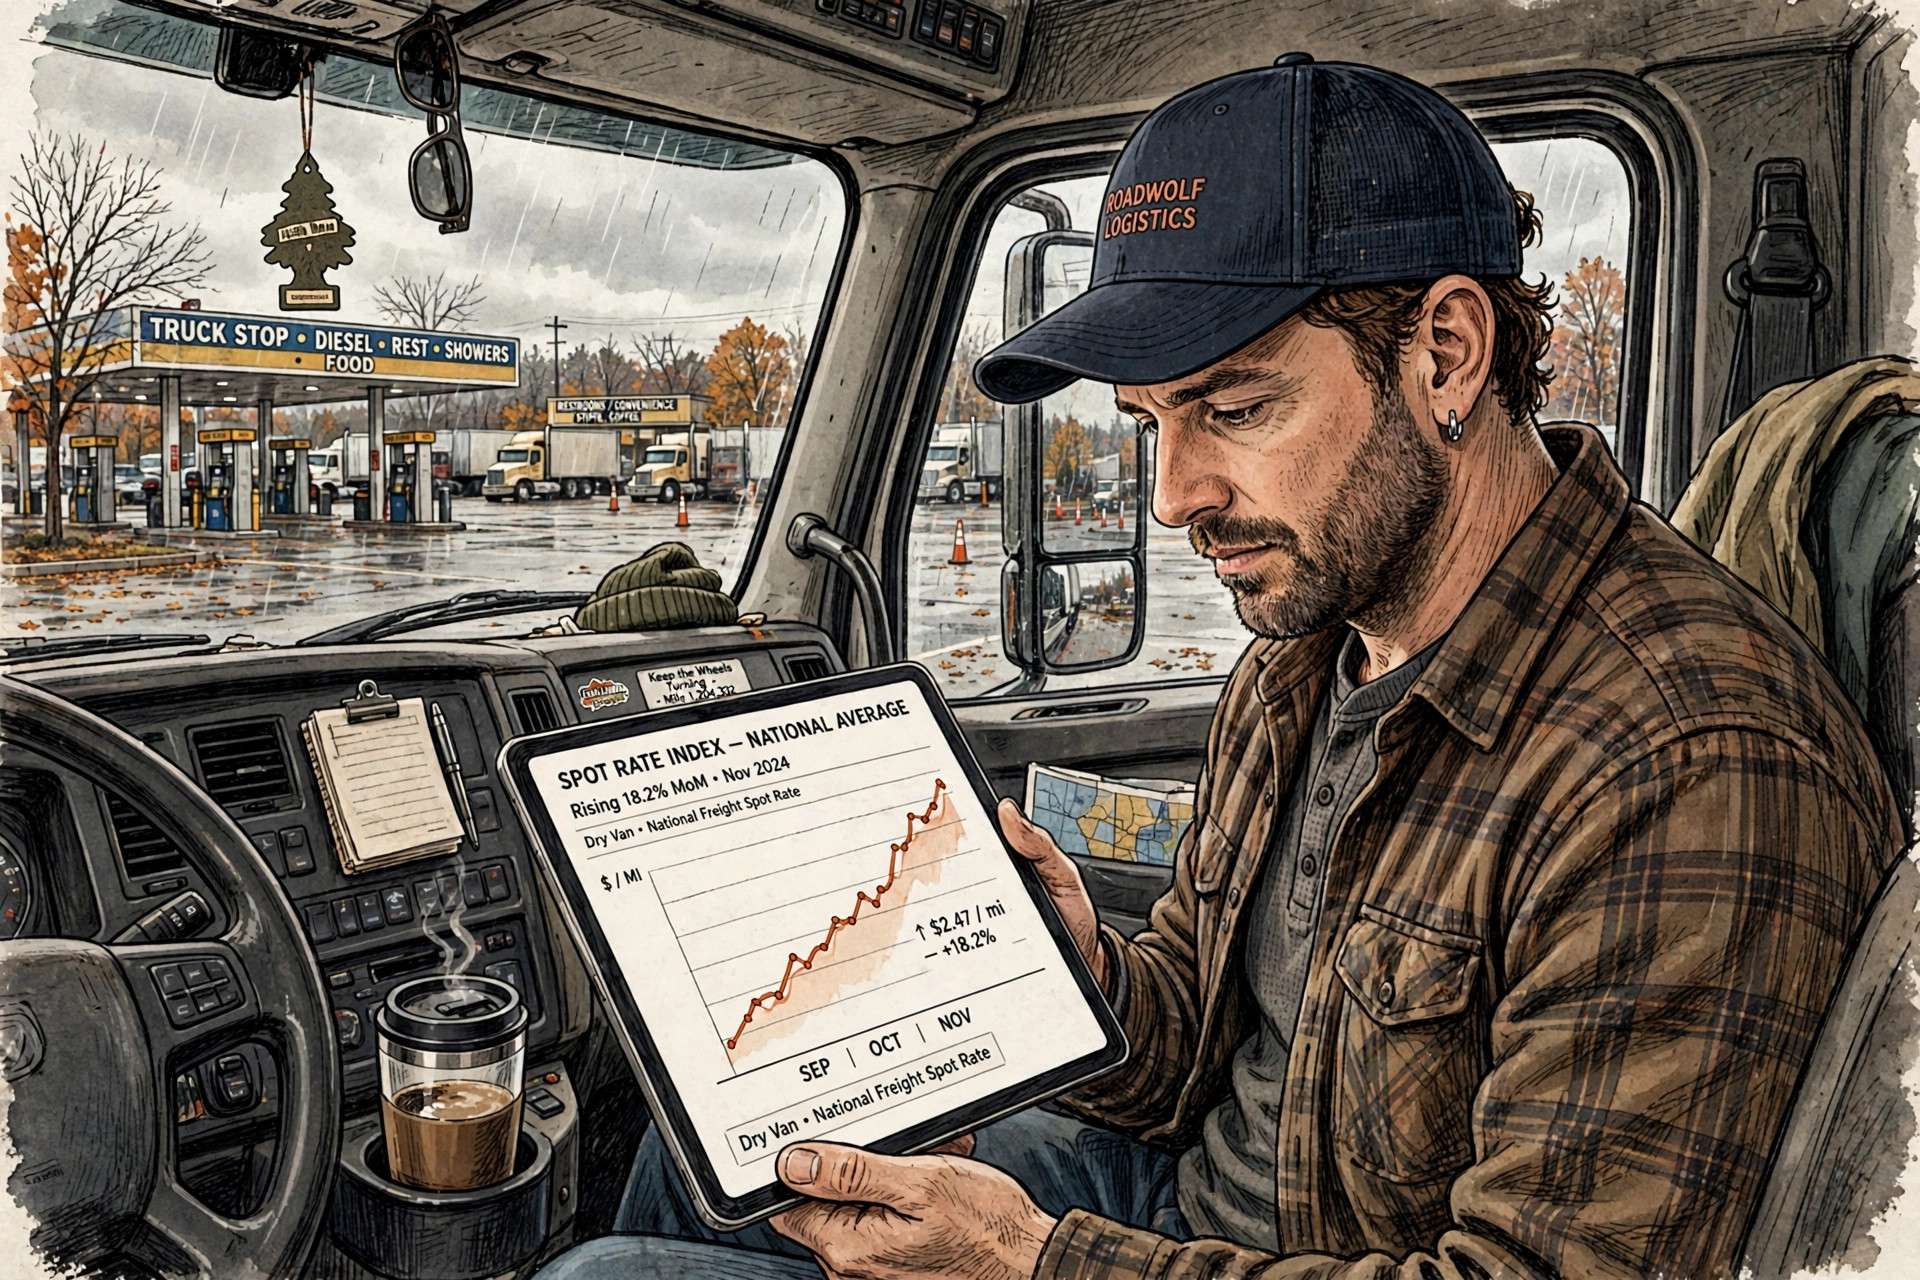
Image: Illustration: AI-generated by CDLWire
Dry van spot rates jumped to their highest level since July in early November, even as diesel prices declined — a split between the rate market and the fuel market that points to capacity, not fuel pass-through, as the driver, according to FreightWaves on Nov. 18.
The numbers frame the divergence precisely. The National Truckload Index, which measures all-in dry van spot rate movement across the United States, rose more than 4% since late October, while diesel truck stop prices fell roughly 3.5% over the same period. Diesel has not seen a sharp increase since early September, yet spot rates have continued to climb throughout that stretch. Julie Van de Kamp, reporting on the data as of Tuesday, Nov. 17, said the early-November move is unusual in its timing as well as its direction: \"It's rare that the NTI starts jumping this early in November ahead of the holidays,\" she said, underscoring that the market is behaving differently than seasonal norms would suggest.
Her explanation of the mechanism is the part of the report every carrier should keep. Spot rates are primarily a function of available capacity and supply and demand, not a straight pass-through of fuel costs — and the current data reinforces that view. \"Carriers can't always pass those fuel costs along unless the market bears it. And so we've also seen in prior cycles when fuel rates or costs have risen and spot rates have fallen, and we're seeing the opposite right here,\" Van de Kamp said. Read in both directions, that is the whole lesson of this fall's market: the same market that would not reimburse $6 diesel in a loose week is now paying more per mile while diesel gets cheaper, because what is scarce is not fuel. It is trucks.
What filled the spot market in early November, on FreightWaves' account, was a last-minute inventory push by retailers. Van de Kamp pointed to the October Logistics Manager Index reading of 66.9 for inventory level growth — the highest reading since 2022. Many retailers delayed bringing holiday inventory into the country, a byproduct of demand uncertainty, rising inventory holding costs and more streamlined supply chains. That compressed ordering window is now pushing freight outside of contracted agreements and into the spot market, adding upward pressure on rates. The leverage in that spill is structural: the spot market represents only a fraction of overall truckload volume — roughly 10% to 25% of truckload freight depending on market conditions, with the remainder moving under contract — so even a modest surge of freight spilling out of contracted agreements can move spot rates meaningfully.
The capacity gauge agrees, with a qualification. National dry van tender rejection rates have been trending lower since July but remain between 10% and 15%, a range Van de Kamp describes as still capacity-constrained: rejection rates above 10% are considered a sign of a tight market, and the current level gives carriers some ability to select freight that fits their networks, without the extreme readings seen over the summer. The truckload market, she said, is \"still really not fully recovered\" and remains in what she characterized as an unhealthy state — but one where carriers retain meaningful optionality heading into the holiday stretch.
This index should not be averaged with the others CDLWire has published this week, because each measures a different thing. Cass' October index, published Monday, is contract-weighted linehaul excluding fuel; DAT's weekly board numbers are broker-to-carrier rates including an estimated surcharge; RXO's Curve figures are a broker's linehaul dataset. The National Truckload Index is an all-in dry van spot measure — the price of the marginal load, today. What the four datasets agree on is the direction of the base market into peak season, and the NTI adds the one fact the others do not carry: the marginal load got more than 4% more expensive in the weeks when fuel got roughly 3.5% cheaper.
For drivers and small carriers quoting spot freight this week, the practical read is to price the capacity, not the pump. A rate justified by fuel surcharges alone leaves money behind in a market where the index rose while diesel fell; the leverage is the rejection range — at 10% to 15%, carriers are still turning down one tender in ten or more, which is the statistical form of the right to be selective about lanes, timing and backhauls heading into the holidays. The caution is in the source of the surge: a compressed, late inventory push is by definition a temporary flow, and the same report calls the broader market not fully recovered. Take the early-November rate while the late freight is moving; do not build December's plan on the assumption that a spillover surge is a season.
Sources
Related coverage
 November 18, 2026 · Fuel & ratesRXO: spot rate growth cooled to 26.2% in the fourth quarter — and that is not deflation, with contract renewals averaging 12%
 November 17, 2026 · Fuel & ratesOctober truckload linehaul rates rose 9.9% from a year ago — and shipments grew for a third straight month
 November 17, 2026 · Fuel & ratesSpot rates rose again in the week ending Nov. 13 — but trucks came back to the board and every load-to-truck ratio fell
Comments
Loading comments…